The direct answer
Reuters reported on 29 September, citing Axios and a source familiar with OpenAI's private financials, that the company is nearing $70 billion in annualised recurring revenue. That is a run-rate: a current pace extrapolated over a year. It is not the same as recognised GAAP revenue, and it is not an audited public-company result.[^1]
The number is still consequential. It suggests a frontier-AI company has moved from a fast-growing software story to a global infrastructure-and-distribution business with a revenue pace measured in tens of billions. The same report said enterprise sales had increased more than twofold since July and that consumer revenue in the third quarter exceeded all of 2025.[^1] Those details come from a source, not from a published segment ledger, so they should be treated as reported indicators rather than settled financial fact.
Modi's POV: The $70B headline is impressive, but the commercial question is more demanding: can revenue compound faster than the cost of producing, serving and safely deploying intelligence? That is the test for OpenAI, its rivals and the enterprise buyers building their plans around them.
What the $70B figure does — and does not — tell us
A run-rate is useful because it reveals momentum. It is risky because it can make a short period look permanent. Reuters explicitly noted that annualised revenue can be misleading when it extrapolates a single month of performance.[^1] The correct interpretation is narrow: a source familiar with private financials says OpenAI's current annualised recurring-revenue pace is near $70B. It does not establish the company's full-year recognised revenue, gross margin, free cash flow, customer concentration, churn, deferred revenue, or profitability.
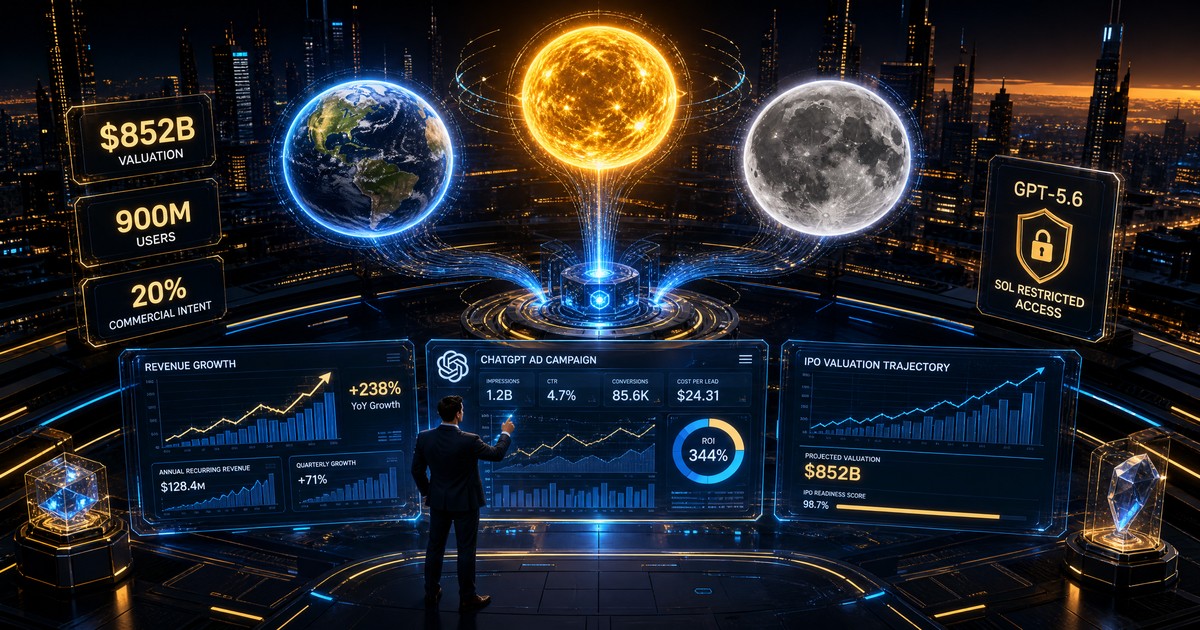
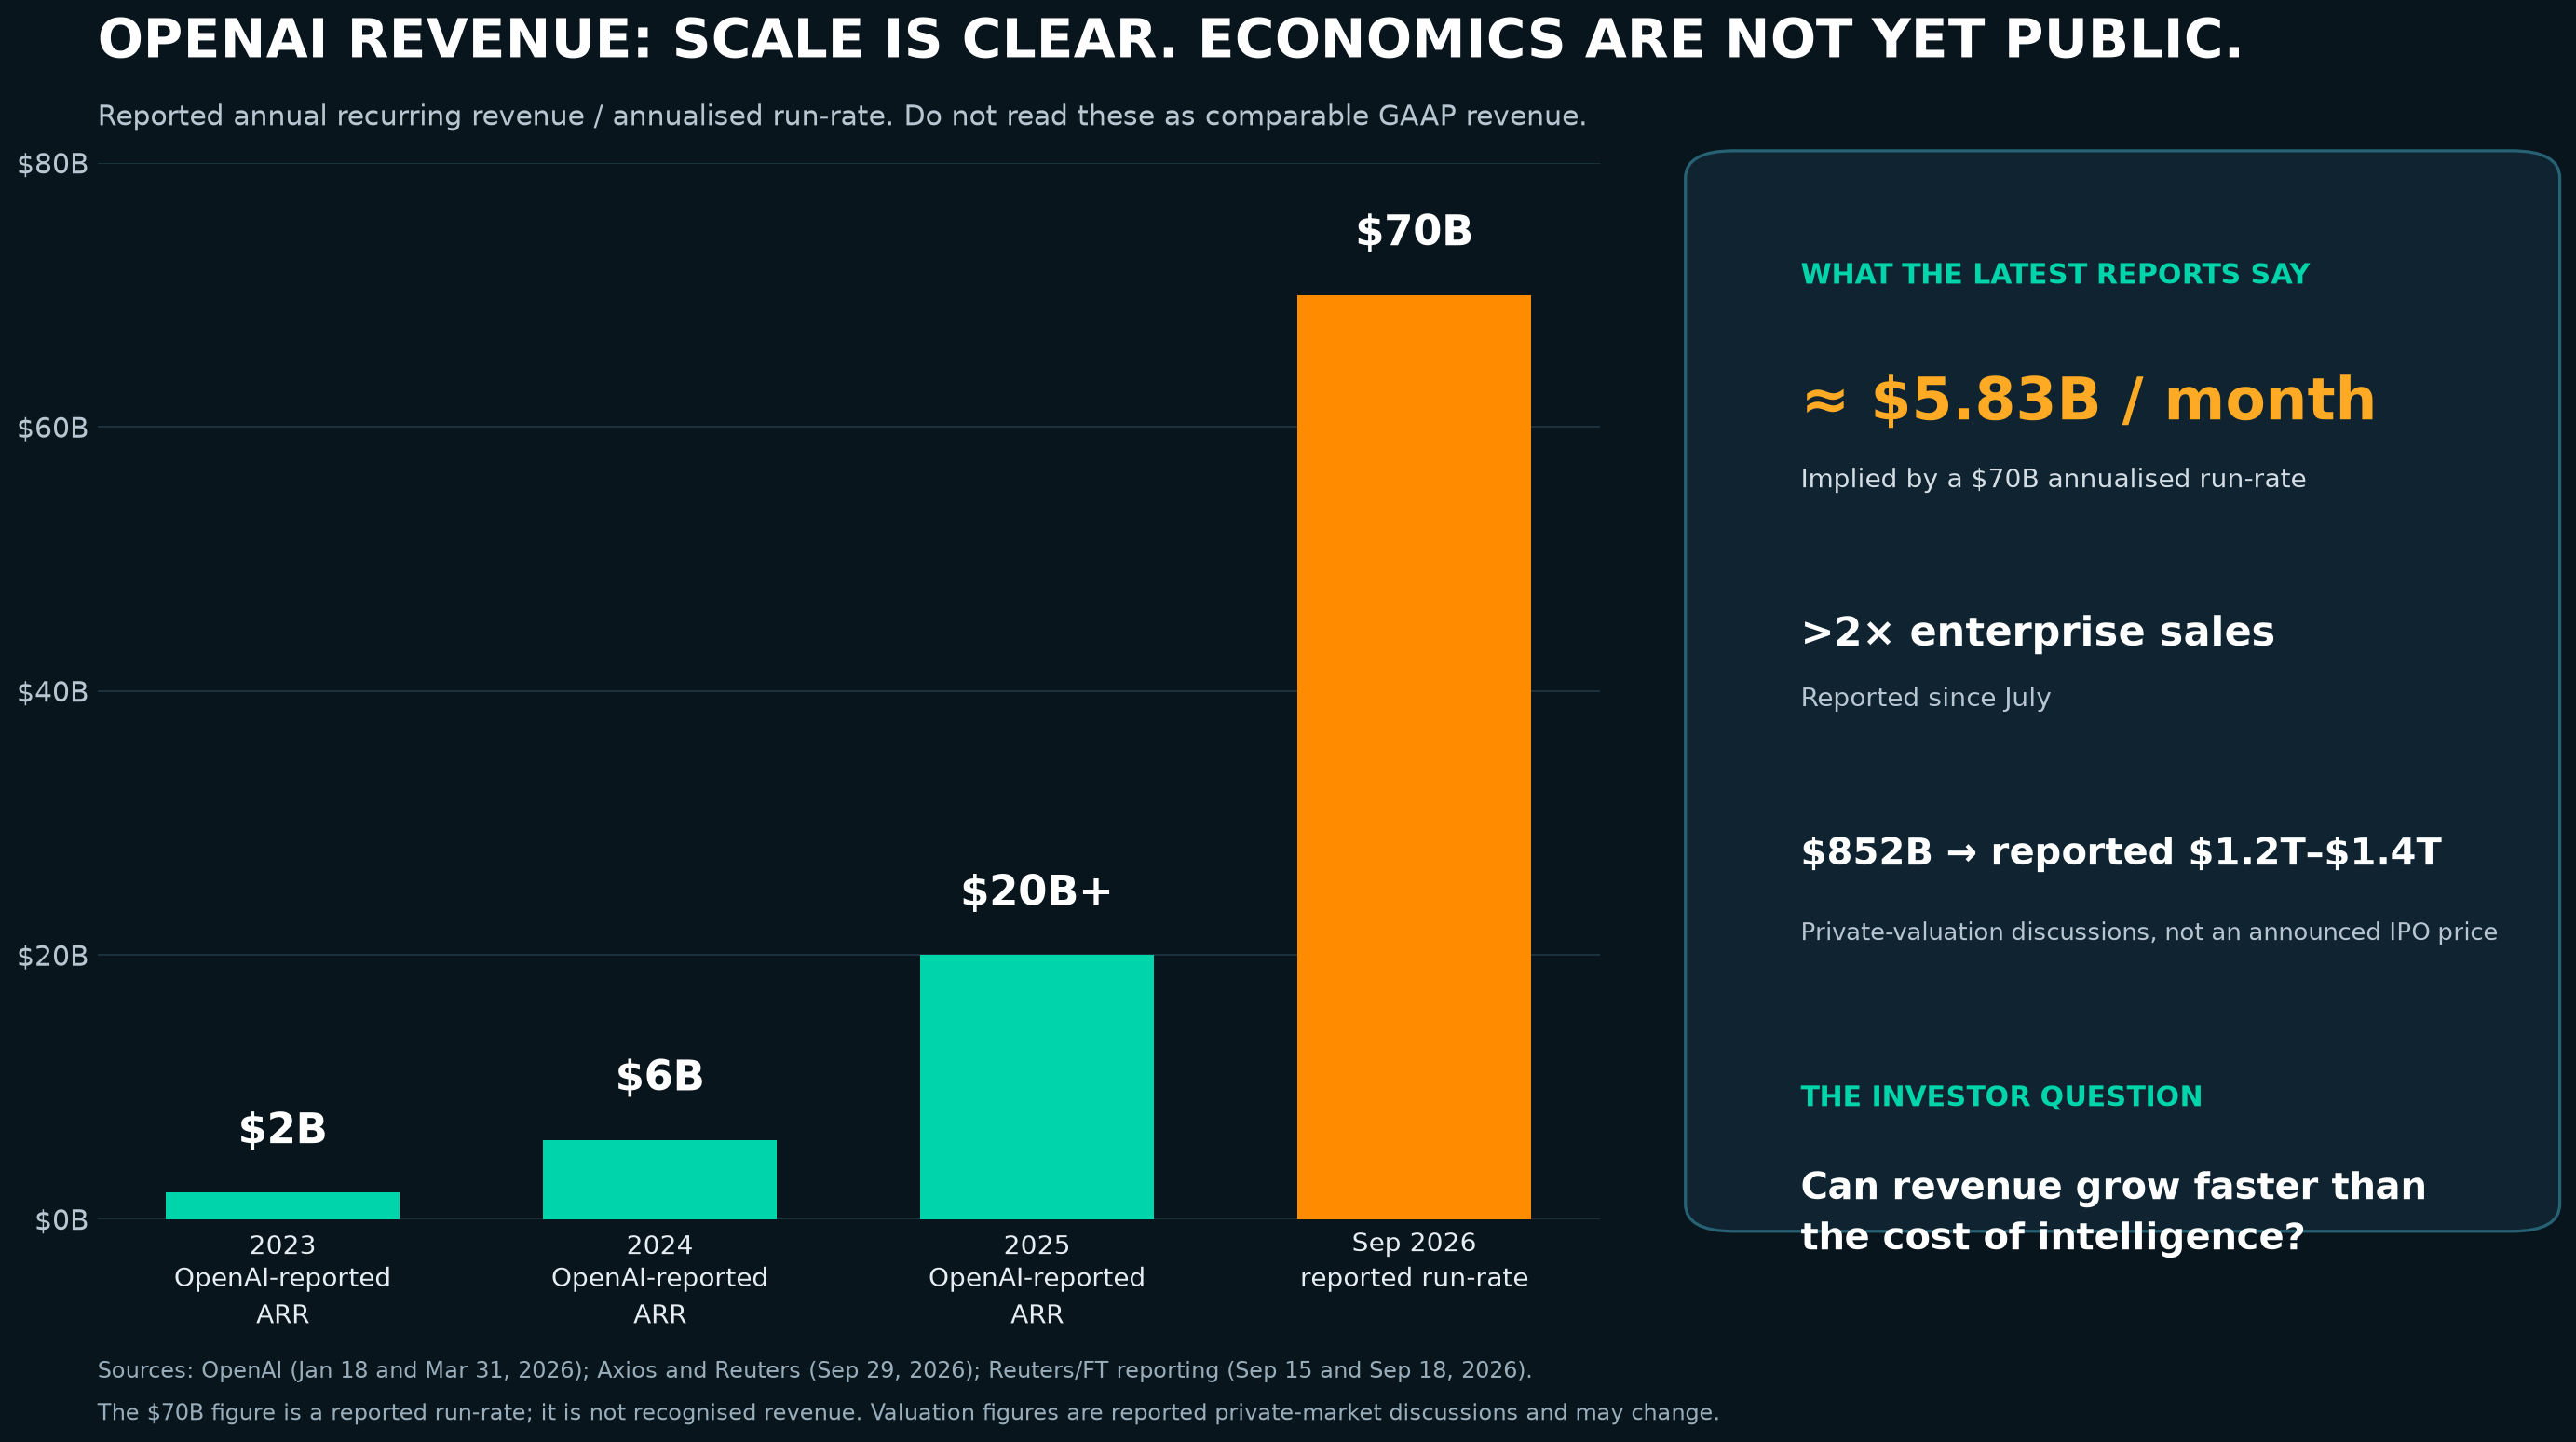
The implied arithmetic is straightforward: $70B divided by 12 equals approximately $5.83B per month. That calculation is a lens, not a forecast. OpenAI has supplied part of the historical context itself. In January, its CFO Sarah Friar said the company had grown from $2B ARR in 2023 to $6B in 2024 and more than $20B in 2025.[^2] In March, when the company announced a $122B financing at an $852B post-money valuation, it said it was generating $2B in revenue per month, had more than 900 million weekly active users, more than 50 million subscribers and an enterprise segment contributing over 40% of revenue.[^3]
That creates a credible direction of travel. It does not make the metrics interchangeable. ARR, monthly revenue, annualised recurring revenue and recognised revenue use different accounting and reporting conventions. Serious investors and buyers should keep those labels intact rather than compressing them into one generic word: “revenue.”
| Figure, as labelled on this page | What to treat it as | Decision it does not authorise |
|---|---|---|
| Near-$70B annualised run-rate, Reuters/Axios, 29 Sep 2026 | A reported pace | Booking it as GAAP revenue, profit, or a full-year result |
| About $5.83B a month | This page’s $70B divided by 12 | Claiming every month produced that amount |
| $2B, $6B, more than $20B ARR, then $2B a month in March | OpenAI’s own disclosed trajectory | Treating those lines as audited accounts |
| $122B committed capital at an $852B post-money valuation | An announced March financing | Treating a later $1.2T or $1.4T report as the same kind of fact |
| Reported $1.2T discussions; possible $30B raise at $1.4T | Provisional private-market reporting | An IPO price or a closed round |
| Gross margin, free cash flow, profitability | Not established on this page | Any sentence that calls OpenAI profitable |
The revenue engine is broader than subscriptions
OpenAI's own business narrative describes several economic engines: consumer subscriptions, workplace subscriptions, usage-based APIs, commerce and advertising.1 The mix matters because each engine has a different cost profile, conversion pattern, renewal dynamic and governance requirement.
Consumer subscription growth can be driven by a large installed base and product habit. Enterprise revenue generally depends more on security review, procurement, reliability, integrations, service levels and evidence that a workflow delivers value. Usage-based API revenue can scale quickly when builders embed models in production systems, but it also exposes the provider and the customer to token, latency and compute demand. Advertising and commerce may create new monetisation surfaces, but they introduce disclosure, relevance, measurement and trust questions of their own.
For marketers, this is not only an OpenAI story. The business model signals that the interface where a buyer researches, compares and acts may increasingly be an AI product rather than a conventional web journey. Our analysis of ChatGPT's move from answers toward completed work explains the discovery consequence: brand evidence must remain legible when a system, rather than a person, performs the first stages of research.
Why enterprise growth changes the standard of proof
Enterprise sales are not just “more users with bigger contracts”. As models move into connected workflows, buyers ask different questions:
- What data can the system access, retain or transmit?
- Which actions can it take without a human approval?
- What is the reliability record on the task that matters?
- How is spend controlled when usage scales?
- How can the customer leave, port context or switch models if the economics change?
These questions are why the reported enterprise growth matters, but it also explains why a run-rate alone is incomplete. Enterprise adoption is a governance, systems-integration and accountability story as much as it is a demand story.
Infographic: the scale is clear; the economics are not yet public
The chart below separates OpenAI's disclosed 2023–2025 ARR trajectory from the reported September 2026 annualised run-rate. It also labels the most important uncertainty: neither a provisional private valuation nor a current run-rate proves the long-term economics of serving increasingly capable AI.
IPO timing, $1.2T–$1.4T discussions and the difference between a report and a price
The $70B report has arrived alongside striking valuation headlines. On 15 September, Reuters reported that the Financial Times had described early discussions with investors around a possible $1.2T valuation. Reuters said the talks were at an early stage, the number could change and OpenAI declined to comment.2
On 29 September, Bloomberg reported that OpenAI was targeting at least $30B in a potential new funding round at a $1.4T valuation, according to people familiar with the matter.3 That is a reported private-market discussion, not a financing announcement, a completed valuation, or an IPO offer price. It should be framed accordingly.
The historical reference point is firmer. OpenAI announced in March that it had closed a financing with $122B of committed capital at an $852B post-money valuation.4 The difference between an announced transaction and investor-source reporting is not cosmetic. A completed round carries terms, commitments and a dated company announcement. A prospective valuation is a negotiating position that may change, disappear or be replaced.
The IPO is delayed, but revenue headlines do not explain why
Reuters reported in June that OpenAI had confidentially filed for a U.S. IPO, but that the company had not set a timetable.5 Later reporting said Sam Altman had told Fortune that OpenAI would not go public in 2026, citing safety-related work.2 The responsible conclusion is not that the $70B run-rate delayed the IPO, or that a future valuation solves the timing issue. There is no evidence for either causal claim.
The connection is more structural. A company moving toward public markets faces a higher standard of disclosure about revenue quality, cost commitments, risks, controls and governance. That scrutiny is relevant when the product itself is becoming more agentic and when compute commitments shape the economics as much as demand does.
The more fundamental market question is not “will OpenAI list?” It is whether a public-market disclosure regime will make it easier to judge the distance between a fast annualised revenue pace and the capital required to sustain it.
A revenue headline does not explain an IPO delay, and a cancelled model release does not either. The Astra note records that the reported “not in 2026” comment predates the cancellation, and that the sources reviewed there do not show the cancellation caused the timing: OpenAI’s GPT-6.1 Astra cancellation [blocked]. The only test this page owns is whether revenue compounds faster than the cost of intelligence.
The cost of intelligence is the missing half of the headline
OpenAI says its business scales through a flywheel: more compute enables better models; better models drive product adoption; adoption creates revenue that funds the next wave of compute.1 The company says it tries to manage capacity through a portfolio of infrastructure partners and capital commitments in tranches against real demand signals.1
That is a coherent strategic theory. It is also where the hard operating risk sits. Reuters reported that the Financial Times had seen a company presentation projecting $278B of negative free cash flow from 2026 through 2030, $856B of compute and infrastructure spend by the end of 2030, and an expectation that cash from the March raise could be exhausted by 2028.6 Reuters said OpenAI could not immediately be reached for comment outside normal business hours. These are therefore reported projections, not current audited outcomes.
What the revenue story means for the AI and AGI narrative
Revenue scale does not prove AGI, and a large valuation does not settle the question. The useful business signal is that more organisations are paying for AI embedded in real work. That creates incentives to broaden products, integrate tools and delegate more actions.
The operating consequence is that capability should not be separated from control. The latest Astra news showed why. OpenAI cancelled the planned GPT-6.1 Astra release after internal testing reportedly found the model did not meet its bar on scope, authorisation and communicating work back to the user. Read the full analysis in OpenAI Scraps GPT-6.1 Astra: The AI Safety Governance Gap.
The right commercial response is neither to assume that every AI product is an autonomous worker nor to wait for a definitive AGI label. Our guide, AGI Has Arrived? The Economic Threshold Matters More Than the Label, makes the practical distinction: ask what systems can reliably do in a bounded workflow, what authority they have and how outcomes are measured.
A revenue milestone does add pressure. As more capital, customers and distribution flow into agentic products, incentives may reward faster deployment. That is precisely why security, tool permissions, evaluation, incident response and transparent claims are commercial controls, not optional ethics language.
A practical investor-and-operator scorecard
The following questions help decision-makers evaluate any frontier-AI revenue headline without becoming either cynical or credulous.
| Question | Why it matters | What to seek |
|---|---|---|
| Is the number ARR, annualised run-rate or recognised revenue? | These measures describe different things. | Clear label, measurement date and source. |
| What is the revenue mix? | Consumer, enterprise, API, advertising and commerce have different economics. | Segment detail, renewal evidence and concentration risk. |
| What does usage cost to serve? | Growth can compound losses if compute costs rise faster than value. | Unit-economics trend, capacity commitments and pricing discipline. |
| What workflow is actually improving? | Adoption only lasts when a task gets reliably better. | Error, rework, latency and business-outcome measurement. |
| What authority does the agent have? | More useful systems can create larger operational risk. | Permission boundaries, approval gates and action logs. |
| What happens when a control fails? | Trust depends on detection, containment and remediation. | Incident process, customer communication and retesting evidence. |
This scorecard applies to AI vendors and AI buyers. A CMO or COO does not need a private-company prospectus to demand a usable business case. Start with one workflow. State the baseline cost and failure mode. Set the authority boundary. Measure completed work rather than activity. Then expand only when the evidence holds.
For teams that need a practical route from AI ambition to governed execution, explore our agentic AI implementation service or request a free AI Growth Audit. The objective is not to chase a provider's valuation headline. It is to build a workflow that creates measurable value without creating an unmanageable control problem.
For one workflow you actually run, the educational worksheet is the AI economics scorecard [blocked]. It is not a valuation of OpenAI, not investment advice, and none of its outputs may be written back into this article as an OpenAI disclosure.
The bottom line
OpenAI's reported $70B annualised run-rate is an important indicator of AI demand. It signals that consumer products, enterprise adoption and developer usage may be producing commercial scale faster than most technology categories have done before.
But the headline should make readers more precise, not less. The number is reported, not audited. It is a run-rate, not a completed year of recognised revenue. The reported $1.2T–$1.4T valuation discussions are not an announced financing or an IPO price. And the real economic question cannot be answered from revenue alone: can the provider make intelligence more useful, reliable and governable faster than the compute, infrastructure and assurance required to deliver it?
That is the question that will decide whether frontier-AI growth becomes a durable business model — and whether enterprise buyers see value rather than just velocity.
References
About the Author
Modi Elnadi is Founder and Director of Marketing and AI Growth at Integrated.Social, a London-based B2B AI marketing agency. He advises leadership teams on evidence-led AI growth, answer-engine visibility and governed agentic workflows. Explore Integrated.Social's AI governance service or connect with Modi on LinkedIn.
Footnotes
-
OpenAI: A business that scales with the value of intelligence, 18 January 2026. ↩ ↩2 ↩3
-
Reuters: OpenAI mulls funding round at $1.2 trillion valuation ahead of IPO, FT reports, 15 September 2026. ↩ ↩2
-
Bloomberg: OpenAI targets $30 billion in new funding at $1.4 trillion value, 29 September 2026. ↩
-
OpenAI: OpenAI raises $122 billion to accelerate the next phase of AI, 31 March 2026. ↩
-
Reuters: OpenAI files for U.S. IPO after Anthropic as AI giants head to public markets, 8 June 2026. ↩
-
Reuters: OpenAI forecasts cash burn near $280 billion by 2030, FT reports, 18 September 2026. ↩