Account based marketing for financial services requires a different evidence and approval model from a generic SaaS sequence. For fintech is ABM that treats risk, compliance and procurement as members of the buying group, and that uses only claims the firm is permitted to make.**
Fintech ABM is not SaaS ABM with a different logo. A committee may be evaluating commercial fit, operational readiness, privacy, information security, regulatory obligations and procurement terms at the same time. The message has to respect that reality from the start.
Who actually buys in a fintech account
There is no universal fintech committee, but a strong account plan makes roles explicit rather than assuming one enthusiastic sponsor can carry the deal. Commercial leadership may own the business case. Operational teams may test workflow fit. Risk, compliance, security and procurement may each need different evidence and a different timing of engagement.
The agency’s job is to help marketing and sales see those requirements before activation. That means a named account set, an agreed owner, a committee hypothesis, an evidence map and a defined route for questions that need a specialist response.
For the general account-based operating model, start with what a good ABM agency in London actually runs. For broader pipeline foundations, see our B2B lead-generation guide.
What you cannot say, and why that changes the creative
The most important fintech creative constraint is simple: an appealing line is not usable merely because it converts. Claims about performance, compliance, security, product capability, customer outcomes or regulated status need an approved source and an owner. That is not a last-minute legal interruption. It is part of the campaign design.
A permitted-claims register should state the approved wording, proof, jurisdictional caveats, review date and exclusions. It gives an agency and an AI-assisted workflow a boundary. Where a question exceeds that boundary, the right action is escalation—not an invented answer.
Read the financial-services AI compliance checklist for a wider view of governed operating requirements. It is an editorial framework, not legal advice.
Modi’s view: compliance is part of the message, not a review step at the end
Account-based marketing for financial services is ABM that treats risk, compliance and procurement as members of the buying group, and that only uses claims the firm is allowed to make.
I would make those functions part of the account plan from the first brief. An agent or email cannot improve a claim it is not permitted to make, and a late legal review cannot repair a message built for the wrong decision-maker.
My view is that compliance is not a separate team waiting at the end of the funnel. In a high-consideration financial-services sale, it is part of what the buyer is deciding. A clear, approved explanation of limitations, controls and process can build trust more effectively than a generic superiority claim.
This does not mean every campaign needs legal language in its headline. It means the account plan and creative should be built from the evidence the business is ready to stand behind.
An agency page that cannot show this register is the mail-merge case, whatever its postcode: what a London ABM agency should run [blocked].
What to ask an ABM agency before you hire one for fintech
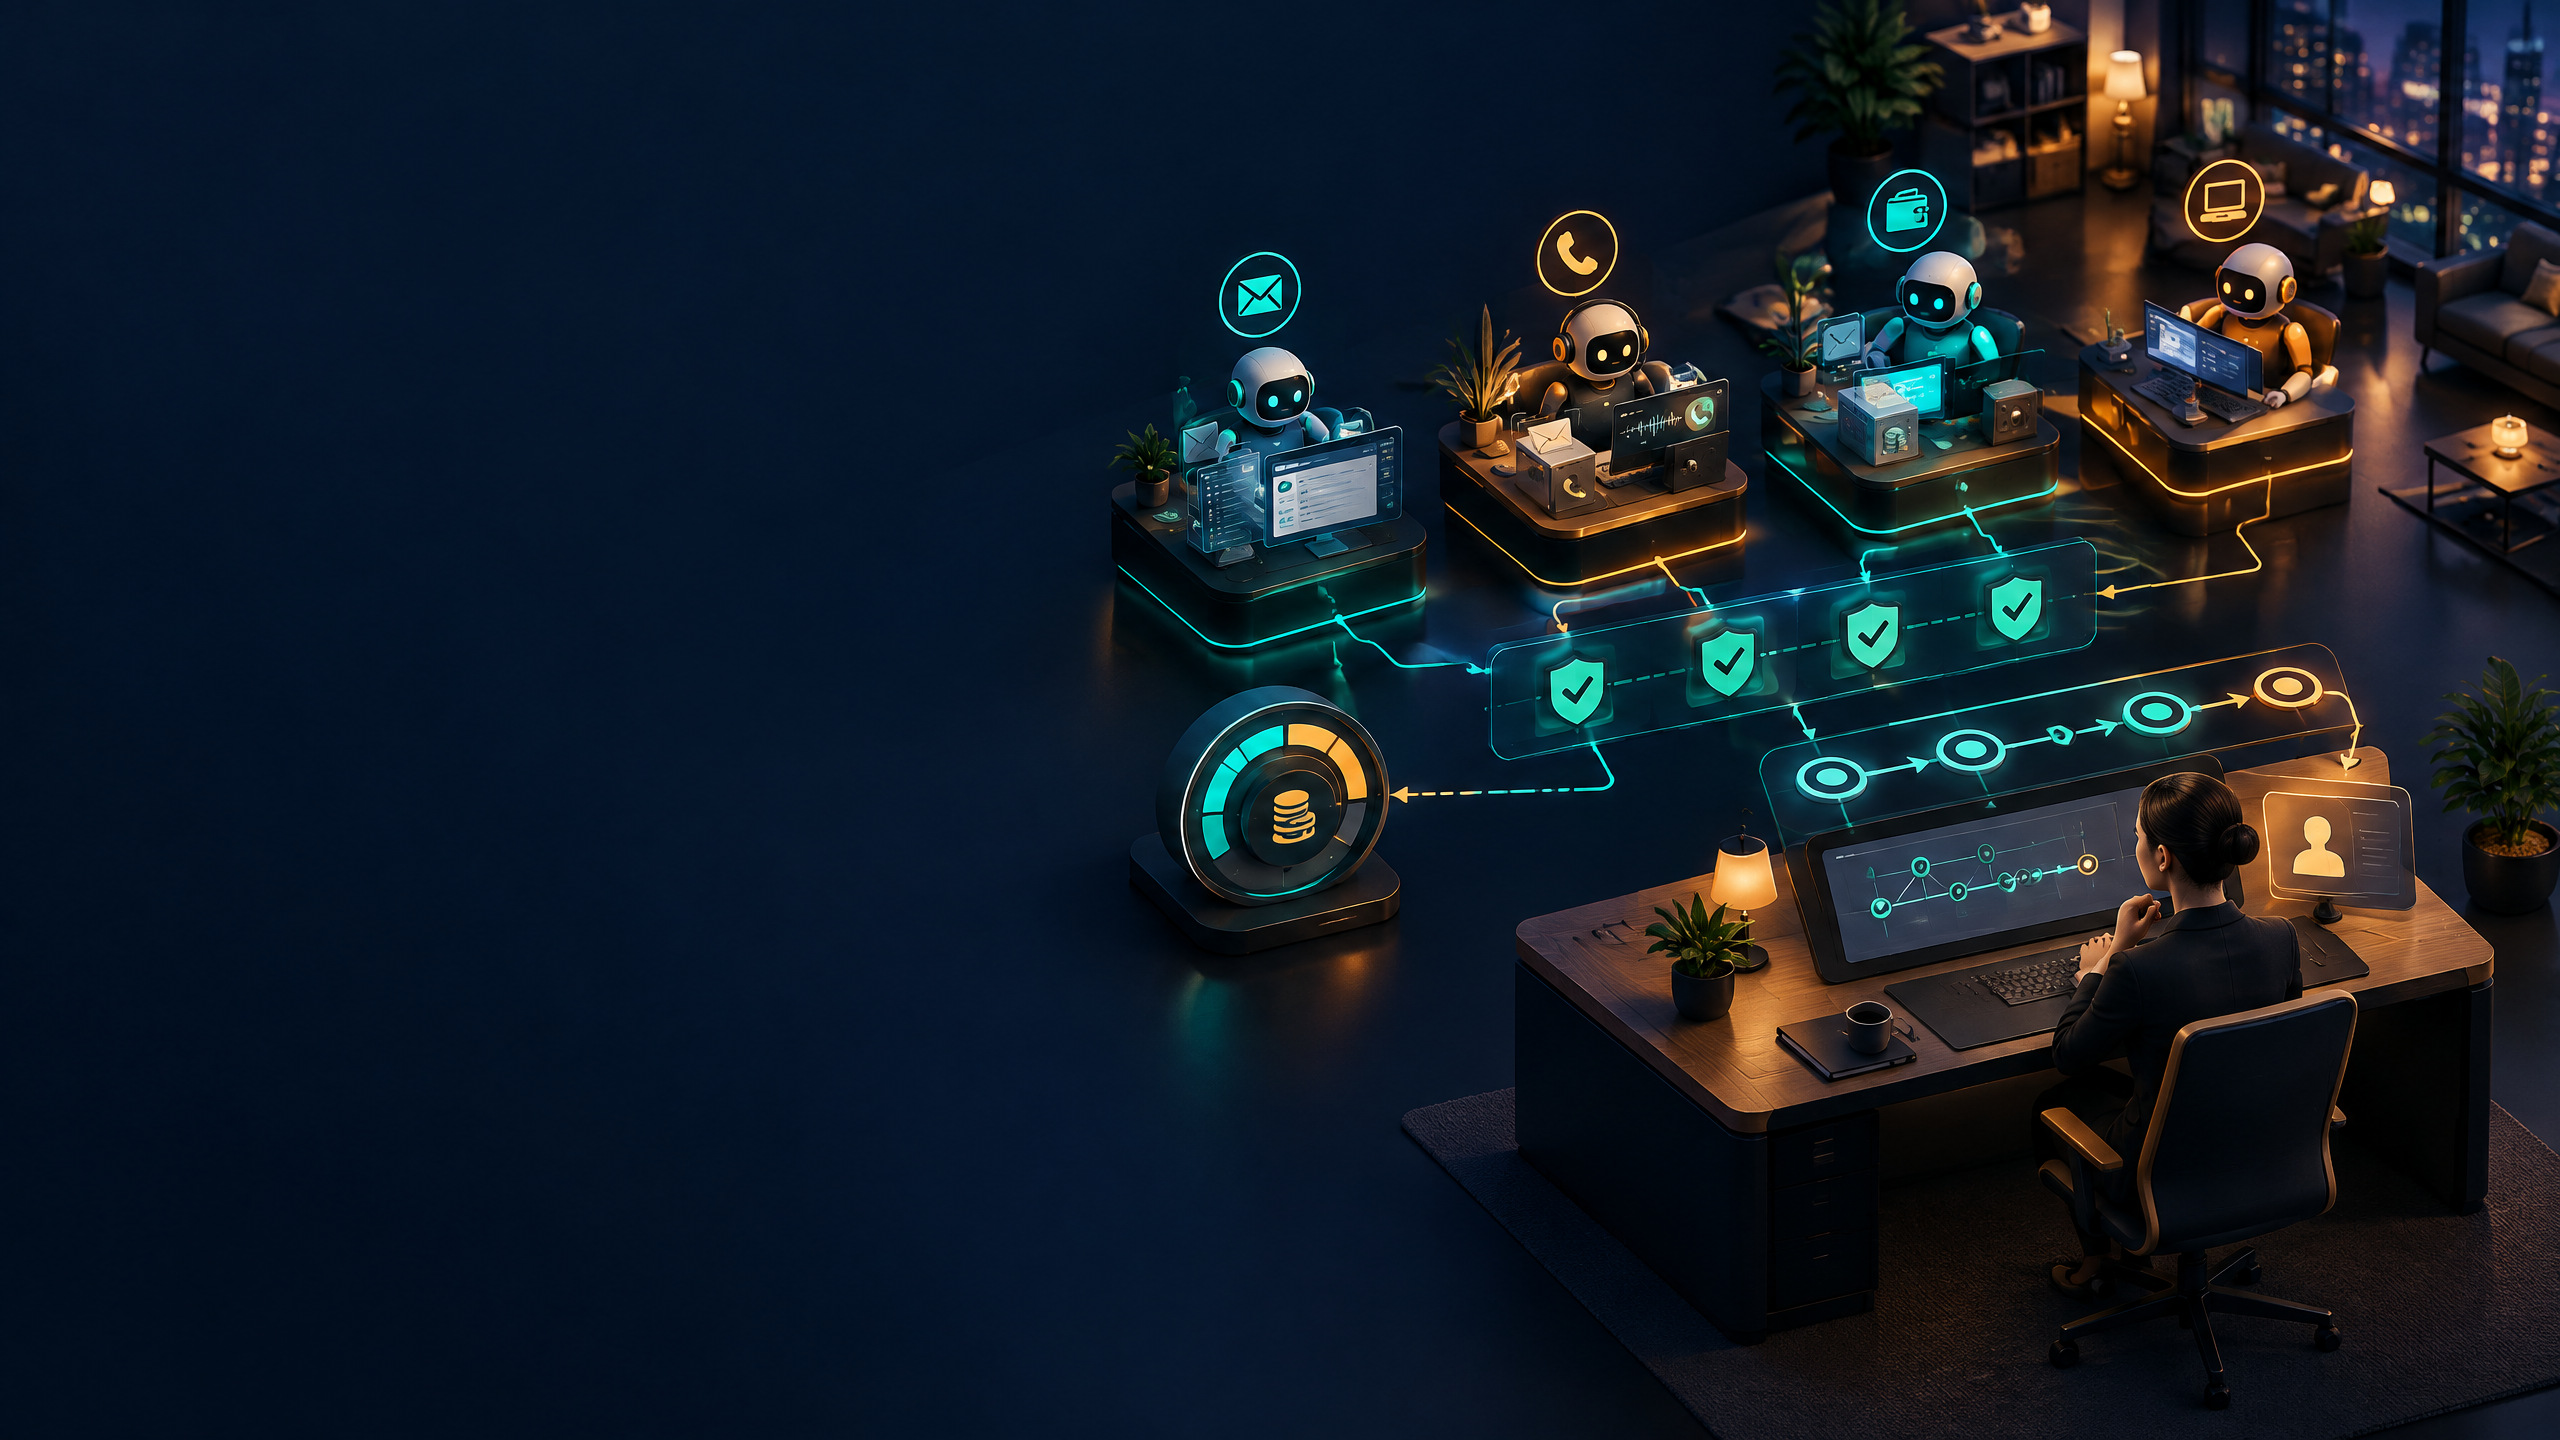
[Image blocked: ABM buying-committee diagram showing named-account selection, role and evidence mapping, approved activation, sales routing and account review, including commercial, operational, risk and procurement stakeholders.]
Decision diagram: use the control path as a planning aid, not as proof of a commercial outcome.
Ask the agency how it selects accounts, maps the committee, maintains approved claims, handles sensitive data, routes specialist questions and documents sales handoffs. Ask what the first pilot will prove and what outcome would stop it. Those questions reveal whether the agency understands a governed buying process or only knows how to generate activity.
AI can help research and prepare structured first drafts. It needs clear permissions, human review and traceable inputs. Our analysis of Agent-Qualified Leads explains why a speedier score is not enough without accountable next steps.
Design a pilot that can answer a commercial question
A fintech ABM pilot should be designed as a decision exercise, not as a compressed version of a full campaign. Before any contact is activated, agree the hypothesis in plain commercial language: for example, whether a particular offer, framed through approved operational evidence, earns engagement from the roles that influence a named buying decision.
Set the unit of learning
Choose an account cohort with a shared reason to be considered, rather than a list assembled from broad firmographic resemblance. For each account, record the trigger or strategic context that makes the conversation potentially relevant, the known and unknown stakeholders, the commercial owner and the limits of available information. Where that context cannot be established, keep the account in research rather than treating it as ready for tailored activation.
Keep the first cohort small enough for sales, marketing and subject-matter owners to review account plans together.
Agree the gates before activation
The pilot needs three gates. The first is a readiness gate: account ownership, permissible data use, claims, proof assets, response routes and review owners are confirmed. The second is an activation gate: only approved versions of messages and assets are released through agreed channels, with a route to pause or amend them. The third is a commercial-review gate: the team examines account fit, committee coverage, response quality, sales follow-up and operational burden before deciding whether to extend, alter or stop the approach.
Pre-agreeing those gates prevents a familiar distortion: treating delivery volume, meetings booked or platform engagement as sufficient evidence that the model should scale. Those signals may be useful observations, but they do not by themselves show that the message survived buyer scrutiny or that the business can support the next stage consistently.
| Gate | Must already be true | If it is not |
|---|---|---|
| Readiness | Account owner, permissible data, claims, proof, response route, and review owner | Do not activate |
| Activation | Only approved versions, and a way to pause or amend | Stop the send |
| Commercial review | Fit, committee coverage, response quality, sales follow-up, and operational burden have been looked at | Extend, alter, or stop. Do not continue only because the sequence is live |
Turn the claims register into a production control
A claims register is most useful when it changes what people may actually build and send. Treat each claim as a controlled item, not a paragraph stored in a shared document. Give it a unique identifier; the exact approved wording; the evidence artefact or internal owner behind it; the product, audience, geography and channel conditions that apply; its review status; and the action required when a recipient asks for more than the statement supports. Record disallowed shortcuts as well as permitted language, particularly where a comparison, outcome implication or absolute assurance would change the meaning.
The practical test is simple: a campaign producer should be able to select an approved claim card and know whether it can appear in a particular email, landing page, briefing note or sales follow-up without inventing interpretation. If the answer depends on informal memory, the control is not yet operational.
Version discipline matters as much as initial approval. Retire superseded variants from templates, label assets pending review, and retain a record of what version was used in each activation. Any AI-assisted drafting should receive the same boundary: it may rearrange approved material within defined instructions, but it should not create proof, extend a claim beyond its stated condition or resolve an ambiguity. Ambiguity belongs in the escalation route, with a named human owner and a defined turnaround expectation.
Map the committee around decisions, not job titles
Committee coverage is not achieved by adding more names to a contact list. The commercial sponsor, operational evaluator, risk or compliance reviewer, security stakeholder and procurement lead may each be deciding something different at different moments. An account plan should therefore identify the decision each role may influence, the evidence that helps them assess it, the likely question that requires a specialist, and the point at which a human conversation is more appropriate than automated nurture.
This approach avoids two opposite errors. The first is forcing every stakeholder into the same benefit story and mistaking exposure for relevance. The second is creating isolated role campaigns that contradict one another or leave the sponsor unable to assemble a coherent internal case. The account-level narrative should remain consistent; the proof and detail should change according to the decision in view.
A useful review asks four questions for every priority account: Who can sponsor the commercial case? Who must be comfortable with the operating and control implications? Who can delay or reshape the purchase? Who owns the contractual or purchasing route? The answers should produce a visible coverage map, not an assumption that one senior contact represents the organisation.
When an account responds, route the signal by its decision type rather than only by lead score. A request for implementation detail, assurance information, commercial terms or procurement documentation needs a different owner, response standard and record. Sales should be able to see what was asked, what may be answered from approved material, what has been escalated and what commitment has not been made. That is how marketing activity becomes a credible contribution to a considered buying process rather than a source of unqualified momentum.
Further reading
We include two contextual Amazon UK resources: The Art of SEO supports the evidence and information-architecture work behind discoverable content, while The Tech SEO Guide is useful for implementation teams maintaining reliable pages. As an Amazon Associate, Integrated.Social may earn from qualifying purchases; recommendations should be assessed for your own context.
Start with a controlled pilot
Use the free AI Growth Audit for a high-level view of website visibility and technical foundations, then book a discovery call to decide whether a named-account programme fits your commercial, evidence and approval environment. No campaign should promise a compliance or pipeline outcome before the conditions are assessed.
About the Author
Modi Elnadi is founder of Integrated.Social, a London AI growth consultancy. Since 2014 he has combined performance media with answer-engine optimisation and agentic lead systems for B2B and B2C brands. These pieces are his working point of view for CMOs, not a vendor press release.