The short answer
Meta Muse has made an old business question newly visible: how much of a company’s margin depends on customers not reviewing an alternative? Reuters reported that Muse reached 2.8 million downloads in its first two weeks, citing Sensor Tower, and that investors worried a large-scale comparison tool could make switching easier. That is an early adoption and market-expectation story. It is not evidence that an AI agent has already changed a company’s realised revenue, churn or customer lifetime value.
The more useful response is to make the customer’s value exchange easier to understand. If an agent helps someone compare a subscription, a travel option, an insurance policy or a financial product, the durable defence is not more cancellation friction. It is accurate information, visible value, clear choices and a retention offer that can survive scrutiny.
Modi’s view: An agent may accelerate the comparison, but it cannot manufacture trust. Businesses that rely on opacity should worry. Businesses that can show continuing value, price fairness and an honest transition path have a more useful starting point than a hidden renewal screen.
Separate the market reaction from the operating result
The Muse story has prompted a wave of discussion about “consumer inertia” companies. That phrase is useful only when it is handled carefully. It describes an economic mechanism in which people delay reviewing, switching or cancelling. It does not mean every customer is trapped, every renewal is harmful or every AI interaction will trigger a cheaper choice.
| What recent reporting supports | What it does not establish |
|---|---|
| Reuters reported 2.8 million Muse downloads in two weeks, citing Sensor Tower | That downloads translate into sustained, delegated purchasing behaviour |
| Reuters reported investor concern about easier comparison and cited market movements | That one agent caused a specific company’s share price, churn or revenue change |
| CNBC reported research on subscriptions, inertia and cancellation friction | That every category has the same retention economics or legal obligations |
| Personal agents can help surface and compare recurring services | That customers will delegate high-consideration financial or insurance decisions without human review |
This distinction should change the leadership conversation. Start with an observable customer journey and a measurable hypothesis, not a headline about disintermediation.
Why consumer inertia is economically material
CNBC reported that a Mastercard and FT Strategies study put average US annual subscription spending at $1,887, and cited a Stanford 2025 paper in which people required to make a decision were about four times more likely to cancel. The article also described the authors’ conclusion that sellers can benefit from both forgotten subscriptions and cancellation friction.
Those figures are useful because they name a mechanism: decision avoidance can support recurring revenue. They are not a forecast that Meta Muse will remove that mechanism across the economy. A household may still value convenience, bundled benefits, service history, trust, advice or a relationship that a price comparison cannot capture.
The strategic question is therefore not “how do we stop an agent from comparing us?” It is “when a customer is prompted to reconsider us, can we show a credible reason to stay?”
Four sectors where the test will look different
Subscription businesses: make the renewal legible
A consumer-facing subscription may be the clearest test. A personal agent can help identify recurring payments and prompt a review. Businesses should make the renewal date, plan level, usage, price changes and cancellation or pause route visible. An inactive customer may respond better to a pause, a lower tier or a relevant value reminder than to a dark-pattern obstacle.
Travel: comparison is already native to the category
Travel buyers already compare dates, fares, cancellation terms, locations and loyalty benefits. An agent may reduce the effort of gathering those inputs, but it does not eliminate differences in inventory, flexibility, customer service or bundled value. The marketing task is to make the relevant constraints readable before the buyer reaches a generic price comparison.
Insurance: advice and eligibility cannot be compressed into a price card
An agent can potentially surface options, but a policy choice involves coverage limits, exclusions, claims service, customer circumstances and regulation. That makes accurate policy information and a clear escalation path more important, not less. Teams should not market a comparison journey as a recommendation unless the underlying advice, eligibility and governance standards are genuinely met.
Financial services: trust, suitability and identity remain part of the journey
Reuters reported that investor concern spread into financial stocks, while one market strategist argued that disruption fears in finance could be overstated. Both observations matter. A customer may compare rates more easily, but a financial decision can still require identity checks, suitability, compliance, education and a trusted relationship. A price-only agent flow is not a complete financial-service operating model.
The value-led margin response
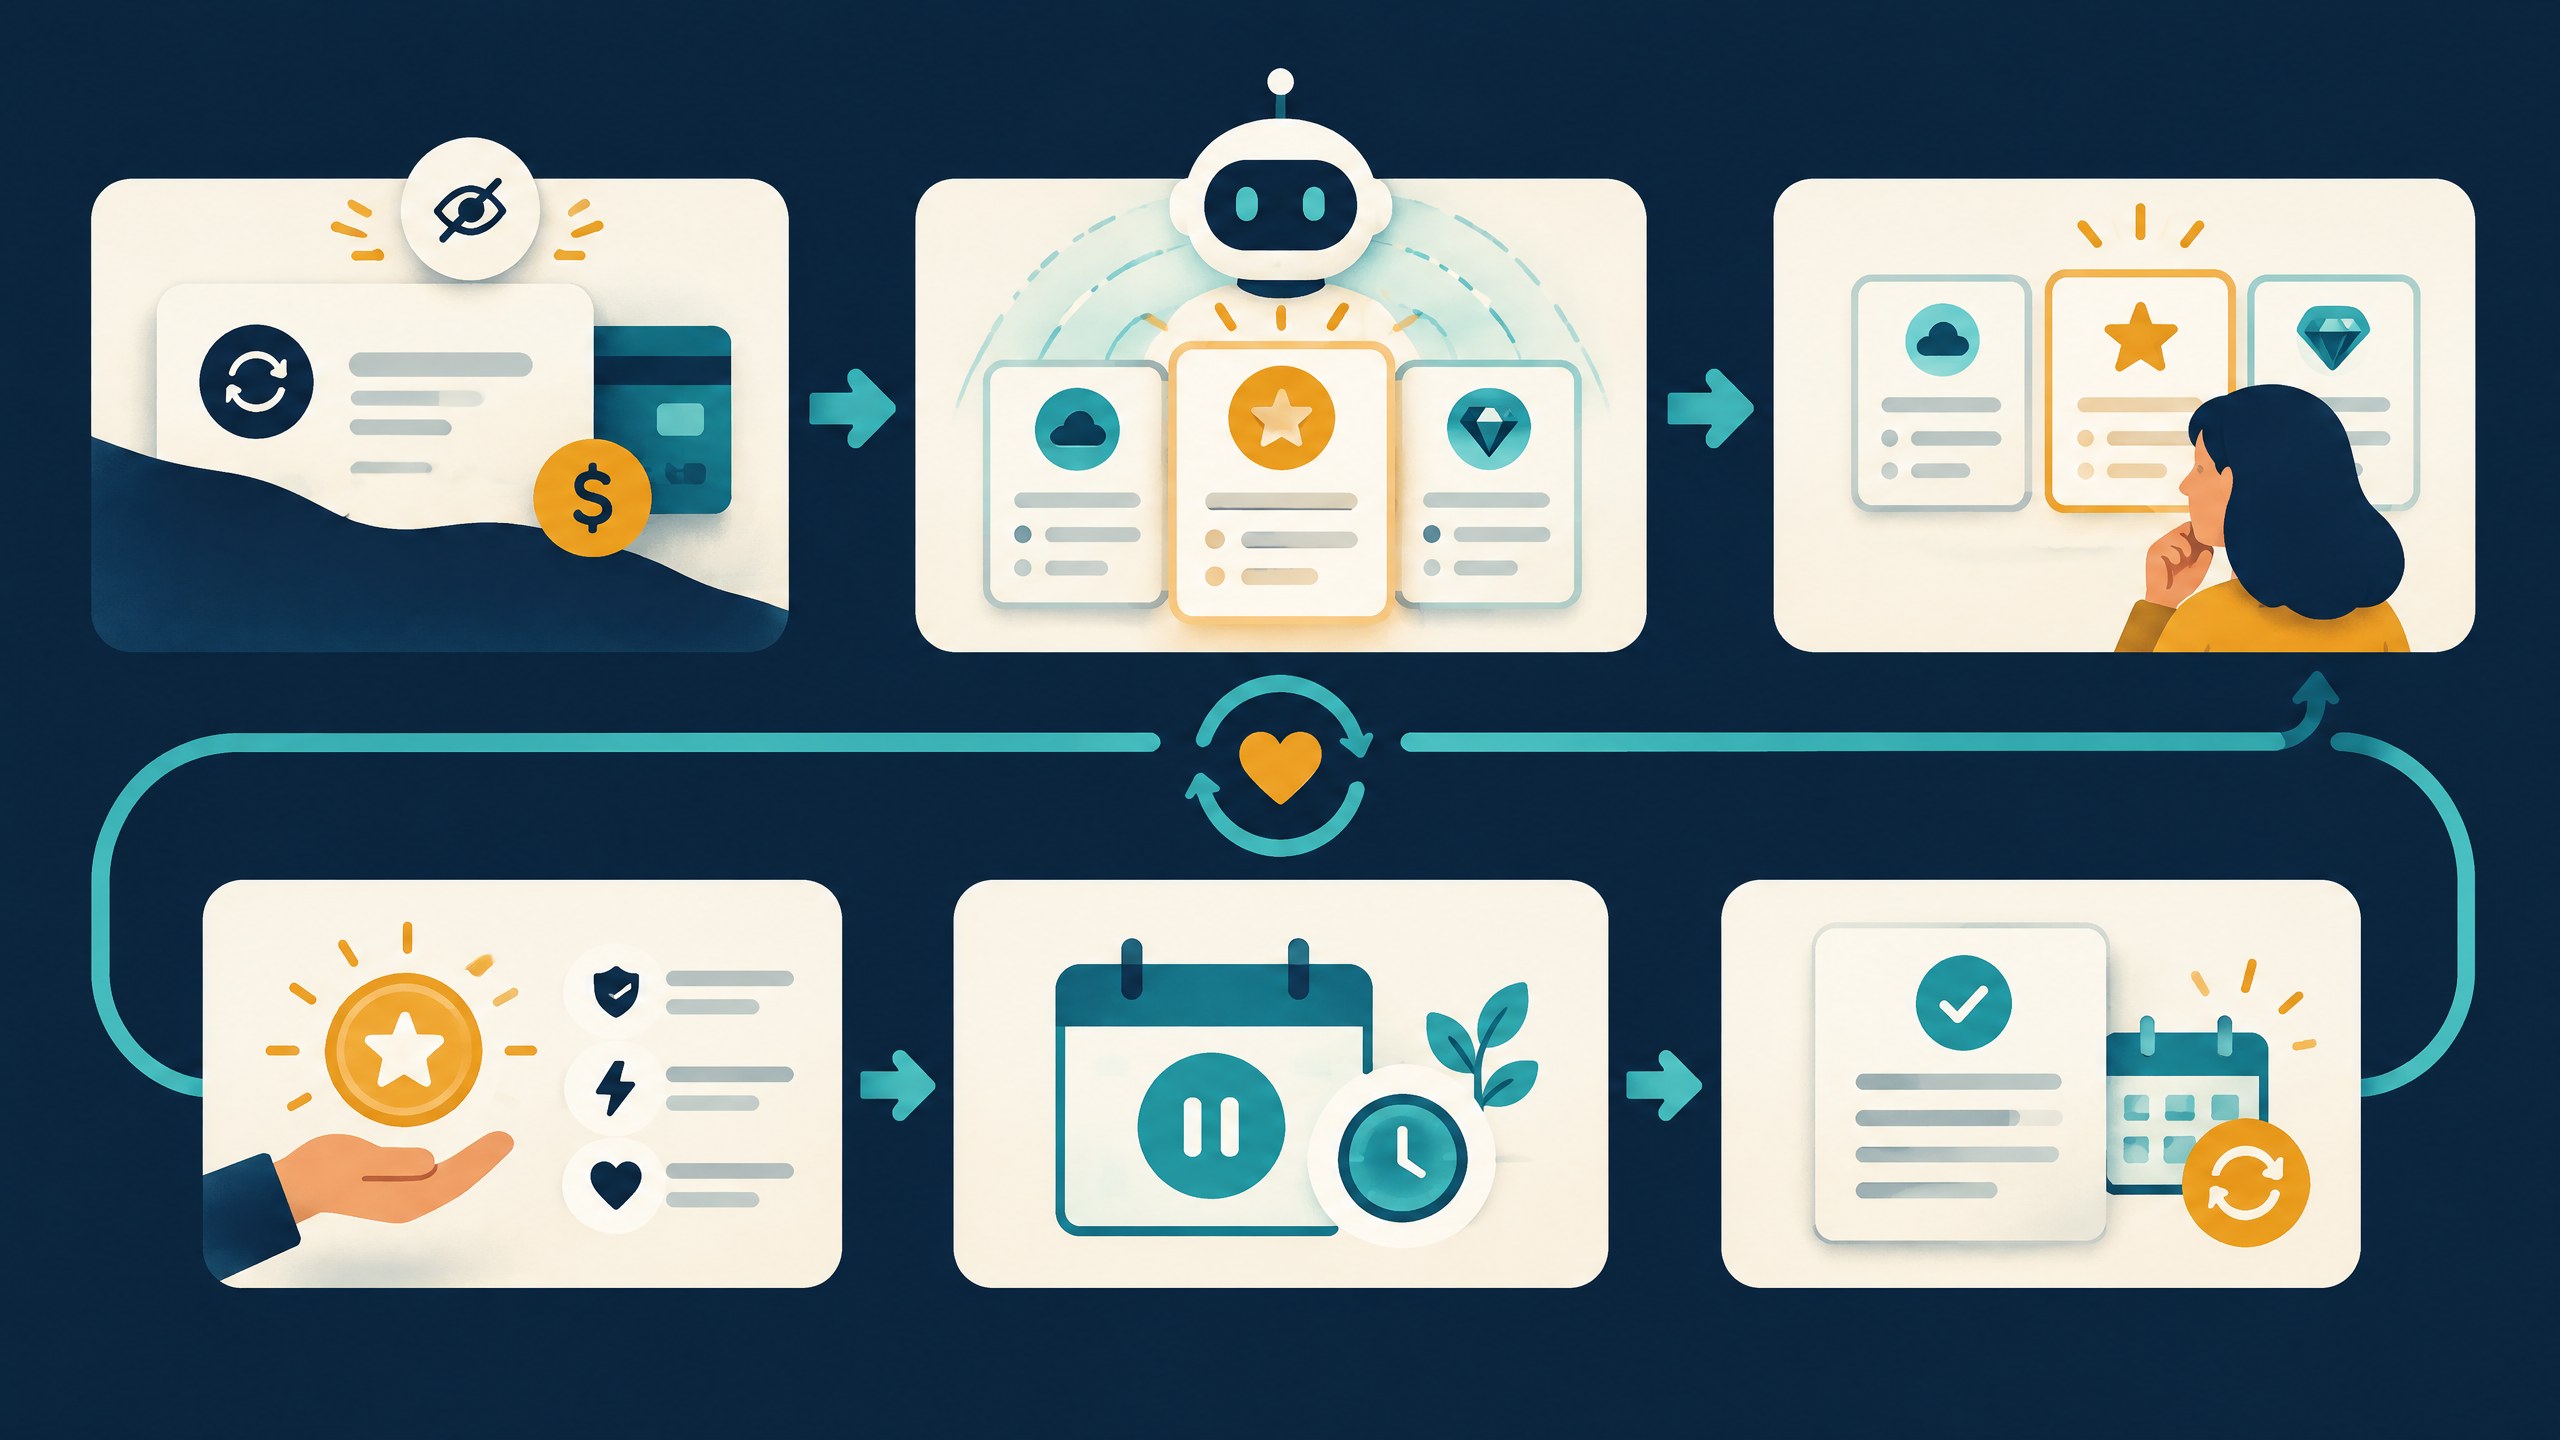
Margin resilience needs a retention system that a customer, colleague or agent can explain back accurately. That system has five parts.
| Design choice | What a customer should be able to see | What the business should measure |
|---|---|---|
| Clear commercial facts | Plan, price, renewal timing, terms and meaningful differences | Comprehension, support contacts and billing disputes |
| Visible ongoing value | Usage, outcome, service access or benefits relevant to the segment | Engagement before renewal and value-message response |
| Flexible transition | Pause, downgrade, cancellation or advisor handoff where appropriate | Save rate, return rate and complaint rate |
| Truthful comparison | Limits, exclusions and differences without vague superlatives | Qualified conversion and post-purchase fit |
| Governed AI touchpoints | What an assistant can access, suggest and execute | Error rate, escalation time and customer trust signals |
This is not a recommendation to offer every customer a discount. Discounting without a value diagnosis can reduce margin while teaching buyers to wait. The better question is whether the customer receives a timely, accurate reason to choose the right level of service.
A 60-day test instead of a grand prediction
A practical test can start with one customer segment and one decision moment. For a subscription business, that might be the renewal email; for a travel company, the date-change journey; for an insurer, a policy review; for a bank, a savings-rate explanation. Map the facts a customer needs, the alternatives they will see, the action they may take and the human route if the decision becomes complex.
Then measure outcomes with discipline:
- Comprehension: Can a customer accurately state what changes, what they pay and what they receive?
- Choice quality: Are downgrades, cancellations and handoffs handled without preventable support failures?
- Retention quality: Are retained customers actually using and valuing the service, not merely failing to act?
- Margin quality: Does the intervention improve contribution after service, support and incentive cost?
- Trust: Do complaints, reversals or privacy concerns increase when an AI-assisted path is introduced?
This creates an evidence base for a board discussion. It avoids a false choice between “agents will destroy the model” and “nothing has changed”.
Marketing visibility becomes part of retention design
As comparison gets easier, the same information architecture serves acquisition and retention. A buyer needs to understand a service before purchase, at renewal and when an agent asks a follow-up question. That puts more weight on consistent pricing context, clear service definitions, verifiable proof, FAQs and a route to a human who can explain the limits.
That is not just a content issue. It is a commercial evidence problem, and it is where AI marketing strategy and SEO, AEO and GEO meet. The goal is not to force a citation or an agent recommendation. It is to remove ambiguity from the facts that a serious buyer needs to evaluate.
For leadership discussion, The AI Marketing Canvas is a useful Amazon UK Associates resource for thinking about marketing operations and customer journeys. It is not evidence for Muse, subscription economics, financial suitability or a specific commercial result. Integrated.Social may earn from qualifying purchases.
The bottom line
AI agents may make it easier for people to inspect a recurring bill, compare a plan or ask why a price changed. That can expose weak retention design. It does not remove customer judgement, category constraints or the need for trust. Companies should prepare by making value more visible, choices more honest and commercial evidence more consistent, then measure what actually changes.
References
- Reuters: Meta’s Muse rekindles fears over winners and losers as personal AI agent emerges, 23 September 2026, updated 25 September 2026.
- CNBC: Meta’s Muse agent is attacking one of the economy’s most profitable weak spots, 27 September 2026, updated 28 September 2026.
About the Author
Modi Elnadi is the founder of Integrated.Social, a London AI growth consultancy working across B2B, B2C, B2B2C and DTC. Since 2014, he has helped teams connect performance marketing, AI search visibility and governed AI workflows to commercial clarity. His point of view: when a buyer can compare more easily, the best response is not hidden friction; it is proof that the service remains worth choosing. Connect with Modi on LinkedIn or explore Integrated.Social’s approach.