Pricing update, November 19, 2026: Anthropic has priced its IPO at $83 per share, above its earlier $70-$78 range. The upsized 980 million-share base offering is worth approximately $81.3 billion gross, including shares sold by existing stockholders. Nasdaq trading under ANT is expected on Thursday, November 19; closing is expected November 20, subject to customary conditions. Pricing is not a first-trade or completed-closing receipt. Official pricing announcement; updated CNBC coverage; Reuters pricing report.
The reported roughly $1.5 trillion fully diluted valuation is an approximate valuation headline, not company proceeds or verified investor gains. The Gulf-investor analysis below distinguishes the Mubadala-linked secondary-share agreement, MGX financing participation and QIA's investment history. Earlier offering and valuation figures are retained only as labeled historical snapshots. Valuation reporting.
Anthropic IPO price, ANT ticker and November 19 debut
Anthropic's official announcement confirms an $83 offer price and an expected Nasdaq Global Select Market debut under ANT on November 19, 2026. The registration statement was declared effective November 18, according to the company. That does not establish that trading has begun, the transaction has closed or the SEC has endorsed the investment's merits. Anthropic pricing announcement.
The base offering is now 980,000,000 shares: 956,351,354 issued by Anthropic and 23,648,646 sold by existing holders. At $83, the gross offering is approximately $81.3 billion before fees. The company-share portion is approximately $79.4 billion gross; Anthropic receives none of the selling-stockholder proceeds. Underwriters have a separate 30-day option for up to 147,000,000 additional company shares. Closing is expected November 20, subject to customary conditions. Do not combine the public offering with a concurrent private placement and call that total IPO-only proceeds. Official share breakdown; CNBC.
| Offering term | Priced November 18, 2026 | Important qualification |
|---|---|---|
| IPO offer price | $83 per share | Above the former $70-$78 range; not a first trading price |
| Trading date and ticker | November 19 expected; Nasdaq ANT | Pricing does not establish the first trade |
| Base offering | 980 million shares | Company and selling-stockholder shares combined |
| Company shares | 956,351,354 | Approximately $79.4 billion gross before fees |
| Selling-stockholder shares | 23,648,646 | Anthropic receives no proceeds from their sale |
| Gross base-offering value | Approximately $81.3 billion | Before fees; excludes the option and any private placement |
| Underwriter option | Up to 147 million additional company shares | Separate 30-day option, not assumed exercised |
| Closing | November 20 expected | Subject to customary conditions; not a closing receipt |
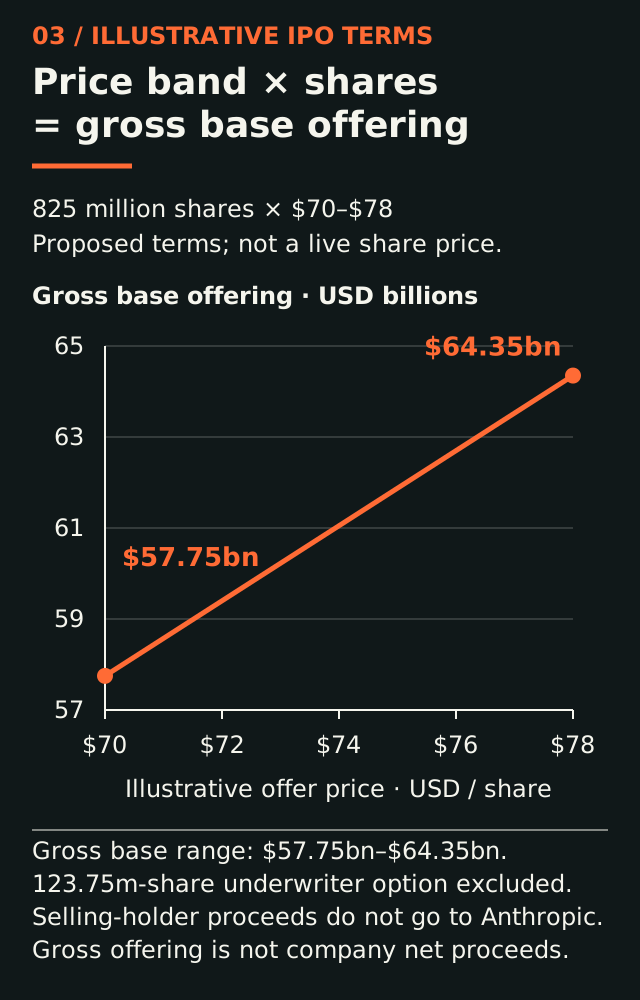
Historical roadshow snapshot, superseded by the $83 price and 980 million-share base offering above. This figure preserves the November 10 proposal, not current terms. Base-offering values are 825 million multiplied by $70 and $78, before fees. Proposed terms are not final pricing, company net proceeds or investment returns. Source: Anthropic roadshow, November 10, 2026.
For readers asking whether they can buy Anthropic stock, public-market access depends on the listing actually commencing and a broker offering the shares. IPO allocations and later market purchases are different processes. This article does not establish availability through any particular broker or recommend a transaction.
Which Gulf institutions invested in Anthropic?
The evidence identifies ATIC Third International Investment Co., described in reporting as aligned with Mubadala, alongside the separately documented investors MGX and Qatar Investment Authority. It does not establish their current ownership percentages. Saudi Arabia's Public Investment Fund should not be presented as a confirmed shareholder from the sources reviewed.
| Institution | Documented relationship | Amount established by these sources | What remains unknown |
|---|---|---|---|
| ATIC Third International Investment Co., Mubadala-linked | Reported March 2024 agreement to acquire FTX-held shares | Nearly $500 million transaction | Current holding and subsequent dilution |
| MGX, Abu Dhabi | Series G co-lead; later Series H participation confirmed by MGX | $30 billion and $65 billion total rounds | MGX's individual contributions and stake |
| Qatar Investment Authority, Qatar | September 2025, February 2026 and May 2026 investments | $13 billion, $30 billion and $65 billion total rounds | QIA's individual contributions and stake |
| Saudi Public Investment Fund | No direct holding verified here | No established Anthropic investment | Whether any later direct relationship exists |
Sources: CNBC stake-sale reporting, March 25, 2024; Anthropic Series G, February 12, 2026; MGX, October 19, 2026; QIA, May 28, 2026.
ATIC and Mubadala: a reported secondary-share agreement
CNBC reported on March 25, 2024 that FTX's bankruptcy estate had agreed to sell the majority of its own Anthropic stake for $884 million. The largest buyer was ATIC Third International Investment Co., described as aligned with Mubadala, purchasing nearly $500 million of shares. The story cited a court document dated March 22 and said the sales still required court clearance. CNBC.
The wording matters. This was a proposed sale of nearly two-thirds of FTX's holding, not a sale of two-thirds of Anthropic. It was a secondary transaction: money paid for existing shares belonged to the seller rather than automatically financing the company. That dated agreement also cannot establish ATIC's present stake or prove which shares it may sell in the IPO.
MGX: a separate growth-financing relationship
Anthropic's February 12, 2026 announcement names MGX among the co-leads of its $30 billion Series G at a $380 billion post-money valuation. GIC and Coatue led the round. Calling MGX a co-lead is supported; saying MGX alone invested $30 billion is not. Anthropic.
There is also more recent primary evidence than the Series G announcement. MGX's October 19 board statement confirms participation in Anthropic's $65 billion Series H, valued at $965 billion. This makes a Series G-only description incomplete, although neither statement discloses MGX's allocation or current ownership percentage. ATIC's 2024 transaction and MGX's later financing must remain separate. MGX.
QIA: three consecutive funding rounds
QIA's September 2, 2025 announcement confirms participation in Anthropic's $13 billion Series F at $183 billion post-money. Its May 28, 2026 statement says QIA first invested in September 2025, returned for February's Series G and increased its investment through May's $65 billion Series H at $965 billion post-money. QIA Series F; QIA Series H.
That is a documented sequence of investment decisions. QIA describes its approach as long-term and focused on AI, software, advanced computing and infrastructure. It is the institution's explanation of its strategy, not independent proof of future performance. The releases do not supply QIA's entry prices, complete share counts or realizable profit.
The investment timeline, without inventing ownership
The timeline separates a reported share-sale agreement from announced financing rounds and the priced IPO with an expected public-trading debut. Different symbols or animation must not turn those categories into equivalent completed events.
| Date | Event | Evidence boundary |
|---|---|---|
| March 22-25, 2024 | Court filing and reporting of FTX's stake-sale agreement | ATIC relationship reported; clearance still pending in the cited story |
| September 2, 2025 | QIA announces Series F participation | First investment confirmed by QIA |
| February 12, 2026 | Anthropic announces Series G | MGX co-lead and QIA participation confirmed |
| May 28, 2026 | QIA announces Series H participation | Third consecutive round confirmed |
| October 19, 2026 | MGX board reviews Series H participation | Later investment confirmed by MGX |
| November 10, 2026 | Anthropic launches IPO roadshow | Proposed shares and price band |
| November 18, 2026 | IPO priced at $83; base offering upsized to 980 million shares | Official announcement; not a first trade or closing |
| November 19, 2026 | Expected Nasdaq debut under ANT | Trading not established by the pricing announcement |
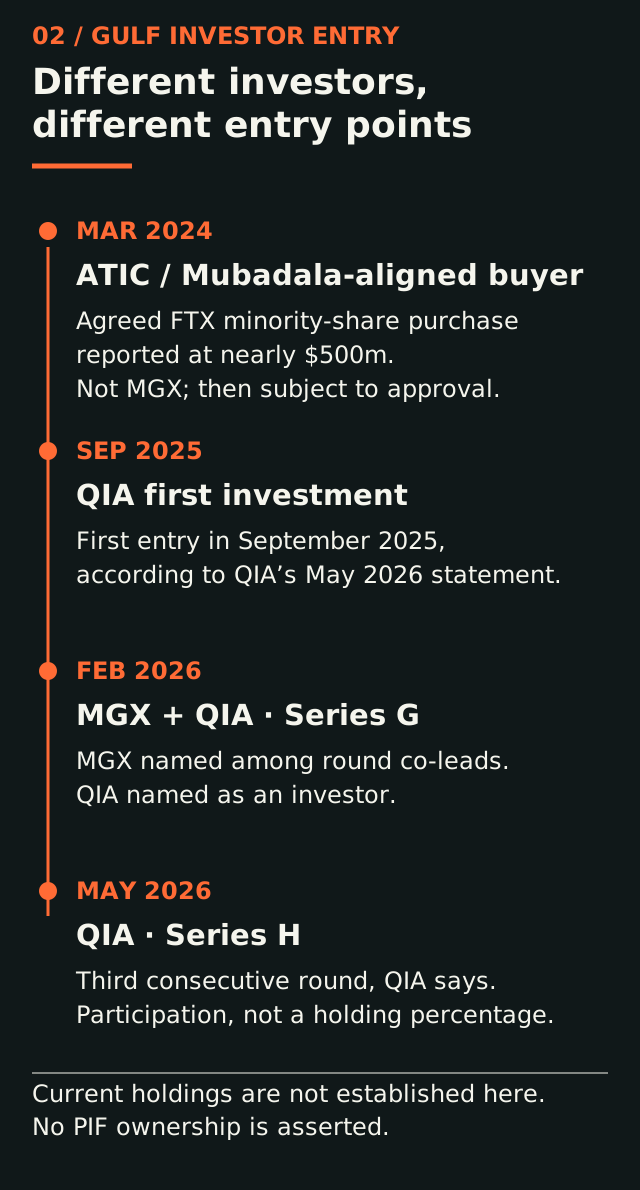
Historical investor timeline prepared before final pricing, not a complete cap table. The table above adds the November 18 pricing announcement; the expected debut remains distinct from a completed first trade. Sources: CNBC, March 25, 2024, QIA, September 2, 2025, Anthropic Series G, QIA Series H, MGX, October 19, 2026 and Reuters, November 18, 2026.
Saudi PIF and the unverified $19 billion takeover claim
No verified source reviewed for this update establishes that Gulf investors offered $19 billion to acquire all of Anthropic and were rejected. CNBC's March 22, 2024 original reporting describes Saudi buyers being excluded from the sale of FTX's minority stake, citing unnamed sources and national-security concerns. Reuters subsequently reported the exclusion explicitly as CNBC's reporting. CNBC; Reuters.
The same CNBC story discusses an $18.4 billion company valuation and nonvoting Class B shares. A valuation is not an offer to acquire the company. Exclusion from a minority-share process is not rejection of a whole-company takeover. The article also says PIF did not immediately respond to a comment request; that does not establish that PIF submitted a bid.
Nor does a historical Saudi exclusion prove a permanent prohibition covering every later transaction. The defensible statement is narrower: direct PIF ownership is not verified by this evidence, and the supposed $19 billion takeover should not be repeated as fact.
Why a roughly $1.5 trillion valuation is not an investor return
Pricing coverage reports roughly $1.5 trillion on a fully diluted basis at $83. Treat this as an approximate reported valuation, not a live trading market capitalization or company cash. The official pricing release establishes the share offering but does not itself supply a fully diluted valuation calculation. Earlier Reuters coverage placed the proposed IPO valuation at up to approximately $1.4 trillion before final pricing. Current valuation reporting; official pricing release; earlier Reuters proposal.
The $380 billion Series G and $965 billion Series H figures were post-money private-financing valuations. Comparing those headlines with a reported fully diluted IPO value does not calculate MGX's or QIA's returns. Different share classes, new issuance, conversion terms, dilution, lockups and transaction timing can all affect the result. A realizable gain also requires an actual sale, not just a higher headline.
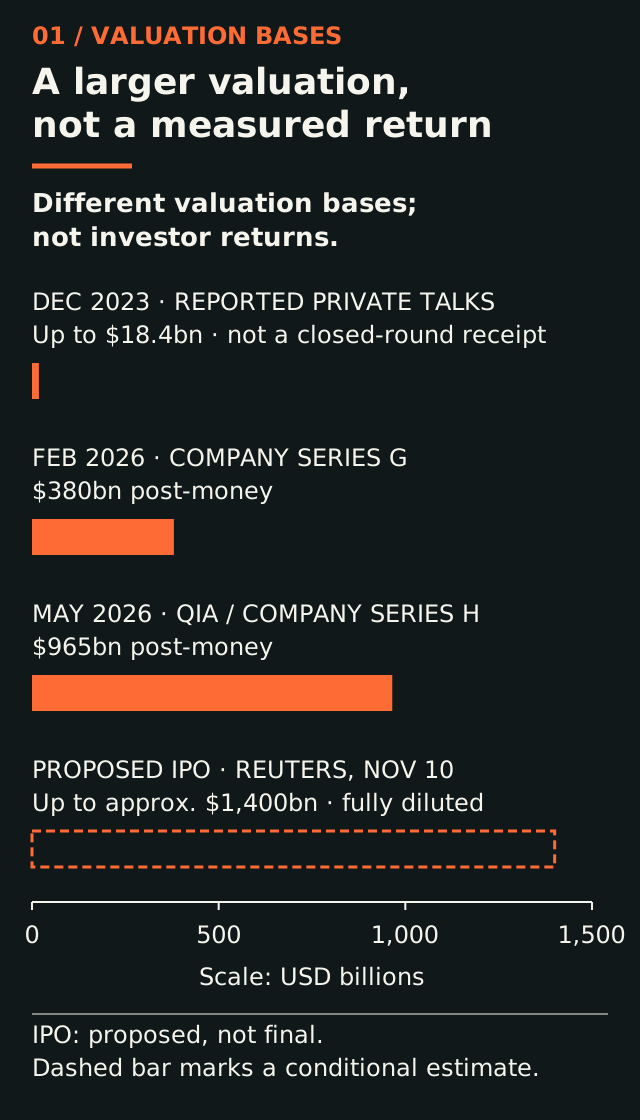
Historical comparison prepared before final pricing: the final column retains the earlier up-to-$1.4-trillion proposal, not the current roughly $1.5 trillion reported valuation. Up to $18.4 billion reported private-financing talks in December 2023 (not a closed-round receipt), $380 billion post-money in February 2026, $965 billion post-money in May 2026 and up to approximately $1.4 trillion proposed fully diluted IPO value. The measures are not perfectly comparable and do not show investor returns. Sources: CNBC, December 21, 2023, Anthropic Series G, QIA Series H and Reuters, November 10.
Compute funding and control: what enterprise buyers should watch
The commercial question is whether financing can support useful, reliable AI delivery. Anthropic's Series G announcement says funding will support research, products and infrastructure; QIA's Series H statement describes expanded compute capacity and product scaling. These are stated purposes, not evidence that every planned system is already operating. Anthropic; QIA.
Funding totals also need careful separation. The following estimate is a historical November 17 midpoint scenario, not final proceeds at $83. The November 17 prospectus estimates $84.6 billion in net proceeds at the $74 midpoint from the company's IPO shares together with a separate private placement. That estimate is not net proceeds from the public IPO alone. Our AI infrastructure economics analysis explains why capacity, utilization and workload cost belong in the same commercial discussion. Preliminary prospectus.
Governance is a different measurement again. The preliminary prospectus describes a founder-controlled entity's Class F share carrying 50.1% of aggregate voting power without economic rights. It also describes Class T rights through which a trustee elects a majority of the board, rather than general stockholder voting. Neither mechanism means a Gulf institution controls Anthropic because it owns an economic stake. Preliminary prospectus.
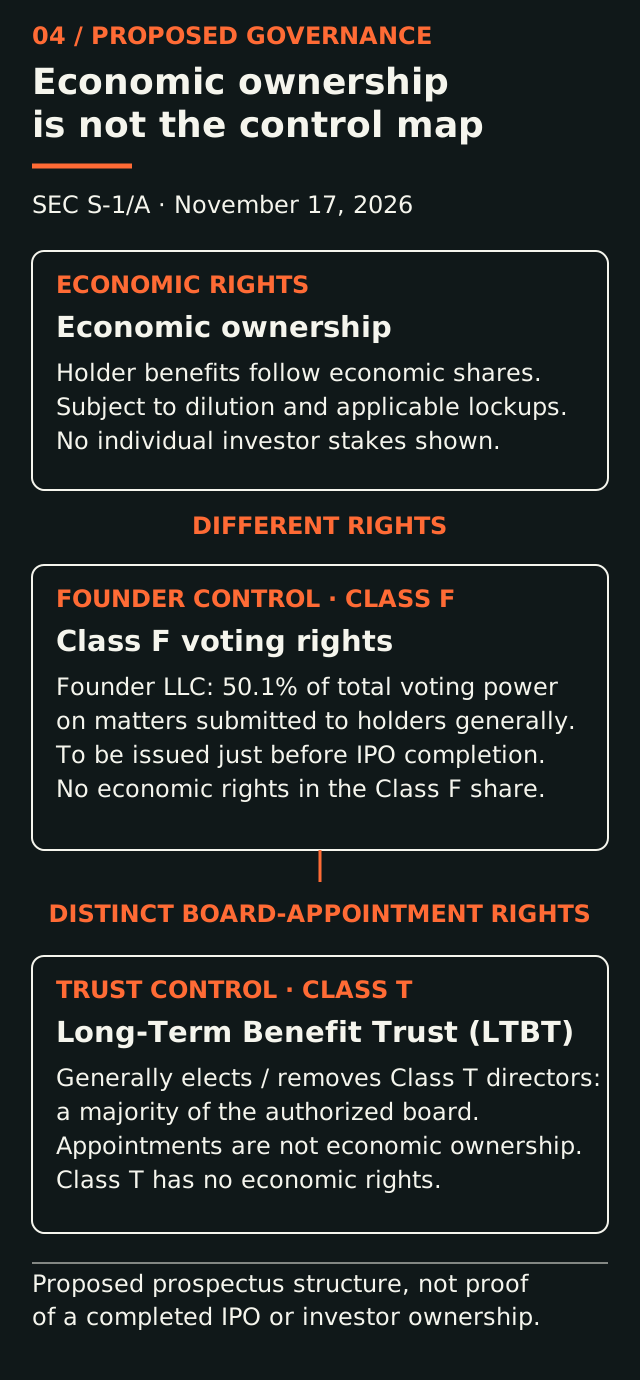
Original explanation of proposed governance, not an ownership chart. Class F's 50.1% voting power is not 50.1% economic ownership. Class T trustee board-election rights are separate. Source: November 17, 2026 preliminary prospectus.
For enterprise procurement, assess performance on your workload, data handling, service commitments, switching costs and failure recovery. Capital availability may support expansion, but it does not guarantee lower API prices, uninterrupted service or satisfactory answers. Competitive pressure, infrastructure delivery and governance obligations remain commercial risks.
Ask a supplier to distinguish an available capability from a roadmap commitment. Test the workflow with representative material and an agreed acceptance standard before increasing its authority. For marketing operations, an accurate research draft and an approved customer communication are different deliverables. An agent that can prepare the first should not automatically receive permission to send the second. Treat the institution backing a vendor as context, not a substitute for these controls.
Apply the same discipline to budgets. A cheaper token rate can still produce an expensive workflow if outputs need repeated correction or integrations create additional work. Conversely, a higher-priced model may be appropriate for a bounded task when its reviewed output meets the required standard. Those are decisions to test with your own records, not conclusions that follow from Anthropic's financing. Name who can approve spending, review exceptions and pause the workflow before expanding it.
Modi's view: measure the workflow, not the funding headline
The strongest lesson is not that early capital automatically wins. It is that frontier AI requires patient financing while enterprise buyers need patient measurement. A large valuation cannot answer whether your sales research, content preparation or customer-support workflow improves a verified business outcome.
Start with one bounded use case. Record the model, input and output volume, review time, failure rate and acceptance standard. Compare useful completed work rather than counting generated drafts. Use the free AI token calculator to estimate documented API costs, then include human review and integration overhead separately. The calculator does not value Anthropic stock.
Our AI marketing strategy service can help connect that evaluation to personas, qualified inquiries and pipeline. For buyer-facing claims, SEO, AEO and GEO services focus on clear evidence and discoverable answers, without promising citations or revenue. Anthropic's priced IPO and expected listing do not confirm an OpenAI IPO timeline; read our OpenAI versus Anthropic IPO background and OpenAI revenue and compute analysis as separate company-specific context.
Editorial disclosure: This analysis by Modi Elnadi follows our editorial policy. It distinguishes official announcements from attributed reporting and proposed terms from completed transactions. Investor participation does not establish current ownership or realized gains. This is informational analysis, not investment advice or a recommendation to buy, sell or hold any security.